

PNC Mobile

- 120.62K Reviews
- 4.5
- Downloads
- 10,000,000+
Our take on PNC Mobile from Appgk
Managing a bank account from a phone is less about flashy design and more about confidence at ordinary, high-stakes moments. I spent time with PNC Mobile as a finance app and found that its main value is straightforward: it puts access to PNC Bank accounts in a mobile setting and helps connect digital banking with nearby branches and ATMs. That sounds simple, but simplicity matters when I am checking a balance before a purchase, looking for cash while traveling, or trying to understand whether a payment has gone through.
The app comes from PNC Bank, N.A., and it is free to use. Its broad availability is reflected in more than ten million installs, while its average rating sits at 4.5 from roughly 313 thousand ratings. Those figures do not prove that every customer will have a smooth experience, but they do suggest that the app has become a familiar tool for a large number of PNC customers. It is rated for Everyone, and the current version is 5.4.1, with support beginning at Android 9.
What using PNC Mobile feels like when trust matters
My first impression is that this is an access tool rather than a financial education platform. It is designed for people who already bank with PNC and want a practical way to reach their accounts outside a desktop browser or physical location. That focus is useful because a banking app should not make routine tasks feel like a scavenger hunt.
The developer’s identity is clear: PNC Bank, N.A. That matters more here than it would with a casual shopping or entertainment app. When I open a banking application, I want an obvious connection to the institution holding my money, not an unfamiliar intermediary whose role I have to investigate. The app’s purpose is also easy to understand: account access, plus tools for finding a nearby branch or ATM.
Best Parts of PNC Mobile
Things to Keep in Mind About PNC Mobile
That trust context comes with an important boundary. PNC Mobile is most suitable for existing PNC customers. If I use another bank, the app cannot replace my primary banking application simply because it offers a polished mobile experience. Likewise, someone comparing banks should not treat the app alone as a reason to open an account. The quality of mobile access is important, but it is only one part of a banking relationship.
In everyday use, I would expect the app to be most helpful in short sessions. I might open it before leaving a restaurant to check whether my available balance can cover an unexpected charge. I might use it while driving through an unfamiliar area, as a passenger, to locate a PNC ATM. I could also check the account before transferring money through another method or before deciding whether a bill payment should wait. These are small moments, but they are exactly where mobile banking earns its place.
News and Features Related to PNC Mobile

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Account access without turning every task into a visit
The strongest reason to install this app is convenience for customers who do not want to depend on branch hours or a desktop computer. A web browser can provide banking access, but a dedicated app is easier to reach when I am already holding my phone. The branch and ATM locator adds a useful physical-world layer: digital banking can tell me what is happening with an account, while the location tool helps me decide where to go next.
That combination is particularly practical during travel. Imagine arriving in a new town and realizing that I need cash or face-to-face assistance. Instead of searching broadly and sorting through unrelated map results, I can use the banking app associated with my account to look for a PNC location. I would still check the displayed details before making a detour, but keeping account access and location discovery in one place reduces friction.
Don't want to read the full review?
There is also a subtle benefit in separating account review from impulse. When I use a general-purpose browser, I may have several tabs, saved passwords, and unrelated distractions open. A dedicated banking app creates a more focused routine: open the financial tool, review what I need, and close it. That does not magically make the phone secure, but it can make my own behavior more deliberate.
Controls I would pay attention to before relying on it
For a finance app, trust is not just a matter of appearance. I want to know what I can control once I am inside the account, how clearly the app presents choices, and whether I can recognize when I am taking an action rather than merely viewing information. PNC Mobile is therefore best judged by the clarity of its account workflow, not by decorative elements.
Screenshots
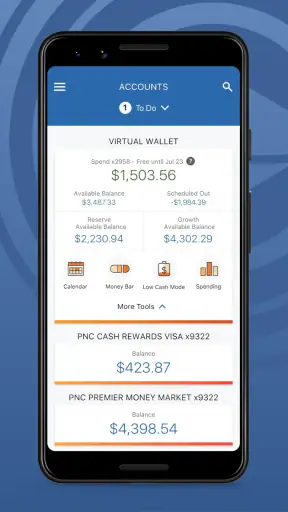
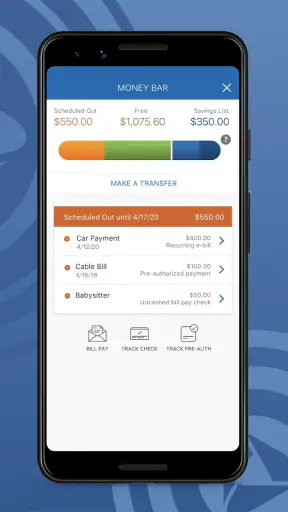
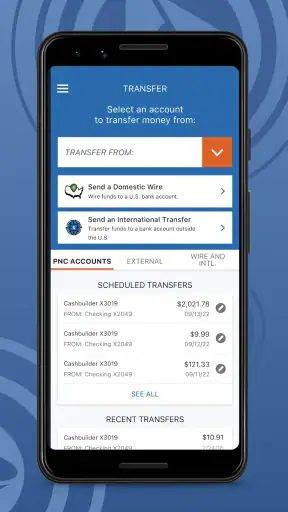
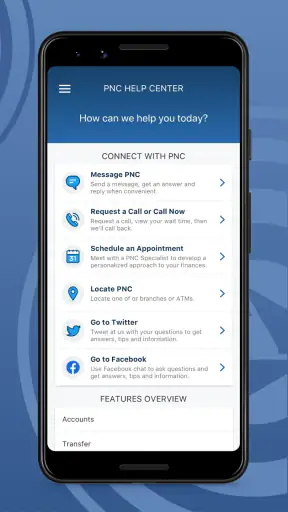
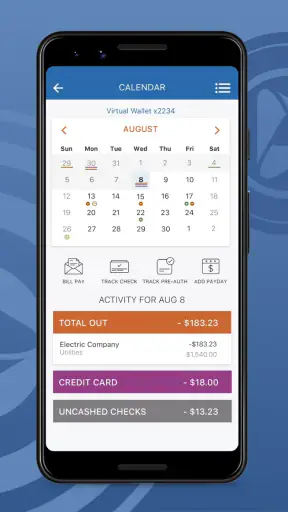
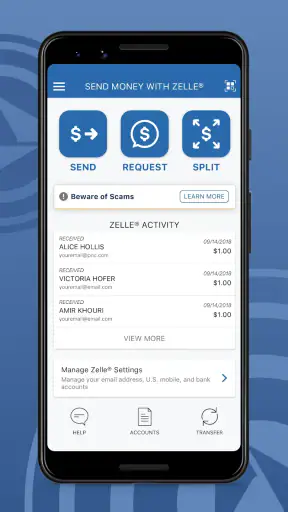
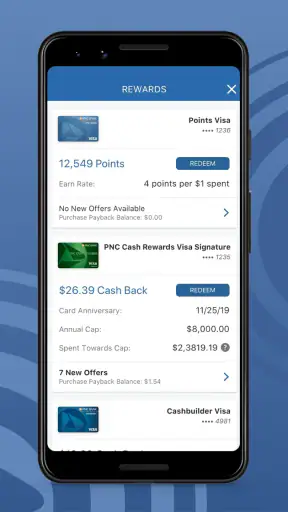
My practical advice is to treat the first session as a setup and inspection session rather than rushing straight into important transactions. I would confirm that the account information shown belongs to me, review the available account areas, and make sure I understand where to find the branch and ATM search. I would also check the phone’s own security settings, because a banking app cannot compensate for an unlocked device shared casually with other people.
A useful habit is to pause whenever a screen changes from information to commitment. Looking at a balance is one kind of activity; sending money, changing a setting, or confirming a financial instruction is another. I would read the final review screen carefully, especially when the amount, destination, or timing matters. This is not a criticism unique to PNC Mobile. It is the discipline I want from any app that can affect my money.
I also prefer to keep notifications purposeful. If the app offers account alerts or similar choices in my account, I would select only the notices that help me act, such as activity I need to recognize quickly, rather than allowing every possible message to become background noise. Too many alerts can make genuine warnings easier to overlook. The important point is that I should make those choices consciously instead of accepting every default without reading it.
Another sensible workflow is to use the app for confirmation, not memory. If I make a payment or perform another account action, I would check the resulting account activity later rather than assuming that a tap automatically means completion. Banking systems can involve processing time, and a visible pending state can mean something different from a completed transaction. The app is most valuable when I use it to verify what happened.
Where privacy and data sensitivity become real-world issues
Finance apps deserve more careful handling than ordinary utilities because even a brief session can expose balances, recent activity, and location-related context. I would avoid opening PNC Mobile on a public screen where someone can read over my shoulder. I would also be cautious when using shared devices, temporary phones, or unsecured networks. These are user-side choices, but they strongly influence the privacy of any banking session.
The branch and ATM finder is convenient, yet location-related decisions deserve attention. If I search for a nearby location while traveling, I should consider whether I want to grant ongoing location access or simply search using a place I enter myself, depending on the choices presented by the app and my phone. A one-time need to find an ATM does not automatically justify permanent access. I value apps more when they let me make that distinction clearly.
I would apply the same care to notifications. A message that reveals an account event on a lock screen may be useful, but it can also expose sensitive information to anyone who sees the phone. I would review the operating system’s notification display settings and decide whether previews should appear when the device is locked. That small adjustment is easy to miss and can matter more than a visual redesign.
Permissions should be considered in context. A location request connected to finding a branch or ATM makes intuitive sense; a request unrelated to that task would deserve more scrutiny. I would read the permission prompt instead of approving it automatically, and I would revisit the phone’s permission manager if my needs changed. The app can provide the banking function, but I remain responsible for deciding how much access the device grants it.
I would also avoid recording sensitive account details in screenshots, notes, or cloud-synced documents just to make future access faster. Convenience can quietly create extra copies of information. A better routine is to use the app when needed, verify the result, and close it without leaving a trail in the phone’s photo library or message history.
How much control the user really has in daily routines
User agency shows up in small decisions: whether I can choose when to search for a location, whether I can control what appears in notifications, whether I can distinguish an account view from an account action, and whether I can stop using the app without losing access to basic banking through another channel. PNC Mobile works best when I treat it as one access point in a wider relationship with PNC, not as the only place where my financial life exists.
That approach is reassuring during technical trouble. If the app is unavailable, my phone has a weak connection, or I simply do not want to use a mobile device for a sensitive task, I should have a backup plan through PNC’s other official channels. The app’s purpose is to make access easier, not to make me dependent on one screen. Keeping that distinction in mind reduces stress when something does not load immediately.
For families, the question is not only whether the app is rated for Everyone, but who is actually using the phone and account. An age rating describes the app’s general content suitability; it does not mean I should hand an authenticated banking session to a child or another household member. I would keep the account tied to my own device security and avoid sharing access credentials.
For older users or anyone who dislikes app-based banking, the branch locator may be more valuable than the account features. It can help bridge the gap between digital convenience and personal assistance. On the other hand, a customer who prefers detailed budgeting, investment analysis, or a consolidated view of accounts from several institutions may find a specialized financial tool more suitable. PNC Mobile is centered on PNC access, not on replacing every kind of money-management software.
PNC Mobile compared with the usual alternatives
The most obvious alternative is PNC’s website in a mobile browser. A browser can be useful when I am on a computer that does not have the app installed or when I want to avoid adding another application. The dedicated app is more convenient for repeated phone access, while the browser may feel better for longer sessions or for people who prefer a larger screen. I would choose based on the task rather than assuming one format is always superior.
A physical branch is still the better option when I need conversation, paperwork, or help that is difficult to explain through a small screen. PNC Mobile can help me find that branch, but it cannot replace the human part of a complicated banking issue. An ATM is similarly preferable when the immediate goal is cash. In that situation, the app’s role is mainly to help me locate a suitable place before I travel there.
General budgeting apps offer a different kind of value. They may be better for someone who wants to see accounts from multiple banks or analyze spending across a broader household picture. I would not expect PNC Mobile to serve that purpose simply because it is a finance app. Its advantage is direct connection to PNC banking, while its limitation is that its usefulness is naturally tied to that institution.
There is also a security trade-off between using a dedicated app and using a browser. The app may be faster to open and easier to keep separate from casual browsing, but installing it creates another piece of software that I need to maintain. The browser avoids that installation, yet it may be less convenient on a phone. In either case, I would use the official access route, keep the operating system updated, and avoid entering credentials through links in unexpected messages.
Who should install it, and who should think twice?
I would recommend PNC Mobile to an existing PNC customer who checks accounts regularly, wants mobile access throughout the day, or often needs to locate a PNC branch or ATM. It is also a sensible choice for someone who wants a focused banking tool instead of relying on a browser bookmark. The free price removes a common barrier, although normal phone connectivity and account-related conditions still apply in real use.
I would hesitate to recommend it as a primary finance app to someone who does not bank with PNC. There is little reason to install a bank-specific application merely to browse its interface. I would also point heavy budget planners toward a tool designed for cross-bank analysis if that is their central need. A person who strongly prefers in-person banking may install it for location help, but should not feel obligated to move every financial task onto a phone.
People using older phones should check compatibility before planning around it. Android 9 is the minimum operating system listed for the current version, so a device below that threshold is not the right foundation for this release. Customers who keep an older phone for emergencies should avoid assuming that every banking feature will remain available there indefinitely.
My cautious verdict after looking beyond convenience
PNC Mobile succeeds because it addresses a clear need without asking me to treat mobile banking as entertainment. Its strongest qualities are direct PNC account access, practical branch and ATM discovery, and the convenience of handling a quick financial check from a phone. The app has a substantial user base, a 4.5 average rating, and a free entry point, but I still view those signals as context rather than a guarantee of a perfect experience.
The limitations are just as important. It is not a universal budgeting suite, it is not a substitute for every branch conversation, and it cannot make careless phone habits safe. Location searches, lock-screen notifications, shared devices, and rushed confirmations all deserve deliberate choices. The app is most trustworthy when I remain an active participant in those choices instead of tapping through prompts automatically.
My everyday recommendation would be to install it if I already use PNC and want a reliable mobile doorway into that relationship. I would begin by checking the available controls, tightening phone security, reviewing notification and location choices, and keeping a non-app backup route in mind. Used that way, PNC Mobile feels like a practical companion for routine banking rather than a replacement for judgment. For the right customer, the real advantage is controlled access at the moment it is needed.
PNC Mobile FAQ
What is PNC Mobile and what can I do with it?
PNC Mobile is PNC Bank’s mobile banking application for managing eligible personal and business accounts from an Android or iOS device. After signing in, you can review balances and transactions, transfer money, deposit checks where supported, pay bills, manage cards, locate branches and ATMs, and receive account alerts. Available features may vary depending on your account type, location, and enrollment status.
Is PNC Mobile safe to use for banking?
PNC Mobile includes security features designed to protect your banking information, such as secure sign-in, device authentication options, encryption, and fraud monitoring. You should still use the official app-store version, keep your phone’s operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or one-time verification codes. PNC may also require additional verification for certain actions or unfamiliar devices.
Can I deposit checks and transfer money using PNC Mobile?
In many cases, PNC Mobile allows eligible customers to deposit checks by photographing the front and back of the check, as well as transfer funds between qualifying PNC accounts or linked external accounts. Deposit limits, availability times, transfer restrictions, and eligibility requirements can apply. Review the confirmation details carefully and retain deposited checks until PNC confirms that they no longer need to be kept.
Does PNC Mobile support mobile check deposit, bill pay, and card management?
The app generally brings several everyday banking tools together, including mobile check deposit, online bill payment, card controls, account alerts, and the ability to report or manage certain card issues. However, not every feature is available for every customer or account. Some services may require enrollment through online banking, additional verification, or separate terms and fees, so check the in-app information before using them.
What should I do if PNC Mobile is not working or I cannot sign in?
If PNC Mobile will not open, crashes, or rejects your sign-in, first check your internet connection and install any available app or system updates. Restarting the device can also help. Do not repeatedly guess your password, since this may lock access. Use PNC’s official recovery options or contact PNC through a verified website, phone number, branch, or secure channel rather than relying on links from unexpected messages.











